Record purpose-built absorption and shrinking condo inventory set the stage for rising rents
TORONTO – October 27, 2026: Urbanation Inc., the leading source of data and analysis on the Greater Toronto Hamilton Area (GTHA) condominium and rental apartment markets since 1981, released its Q3-2026 rental market results today, showing strong signs that the GTHA rental market began to recover during the busiest leasing period of the year.
Q3-2026 HIGHLIGHTS
Record leasing. New purpose-built rentals absorbed 1,911 units in Q3, bringing net absorption for the first nine months to a record 5,092 units, up 22% from 2025. Condo lease transactions also reached a record 54,324 units year-to-date, up 6%.
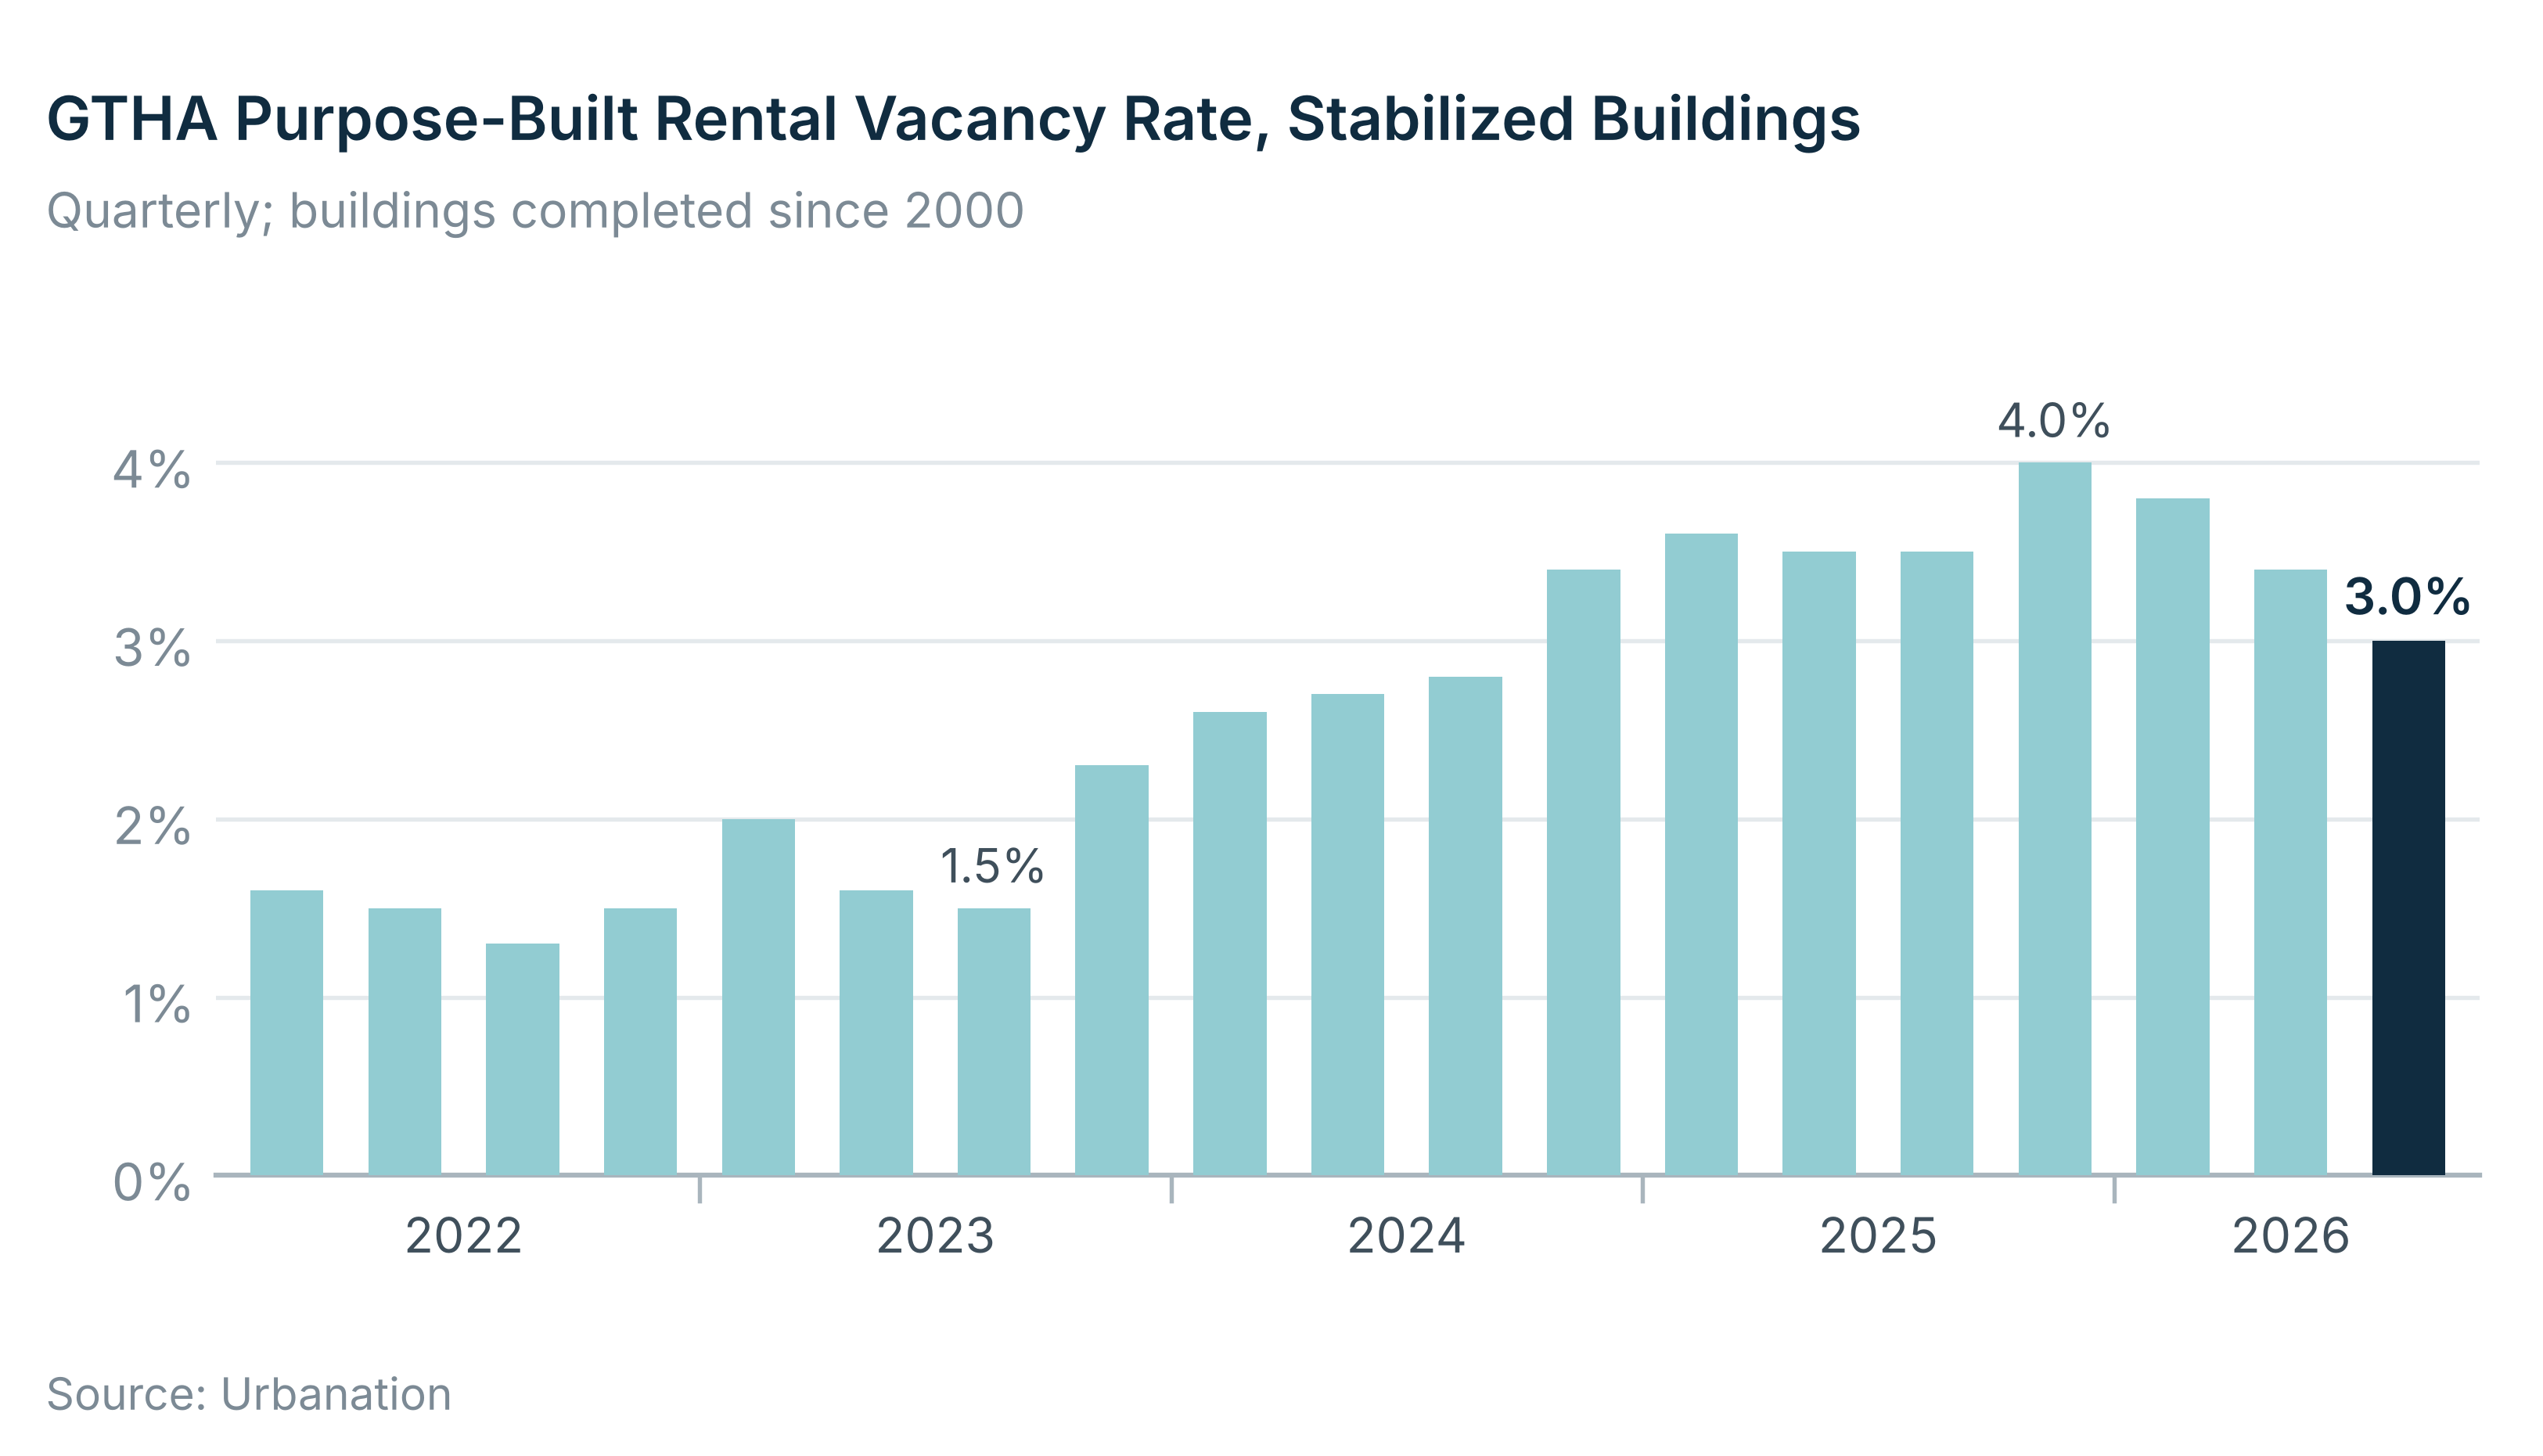
Tighter supply. Purpose-built vacancy fell to 3.0% in stabilized buildings from 3.5% a year ago, and to 5.8% in buildings at least one year old from 6.1%. Active condo rental listings fell 25% from a year ago and are down 43% from their peak, with growth in leasing outpacing growth in listings for five straight quarters.
Incentives pulling back. The share of purpose-built projects offering incentives fell to 60% from 67% in Q2, the largest quarterly drop since Q2-2022, and one month of free rent replaced two months as the most common offer.
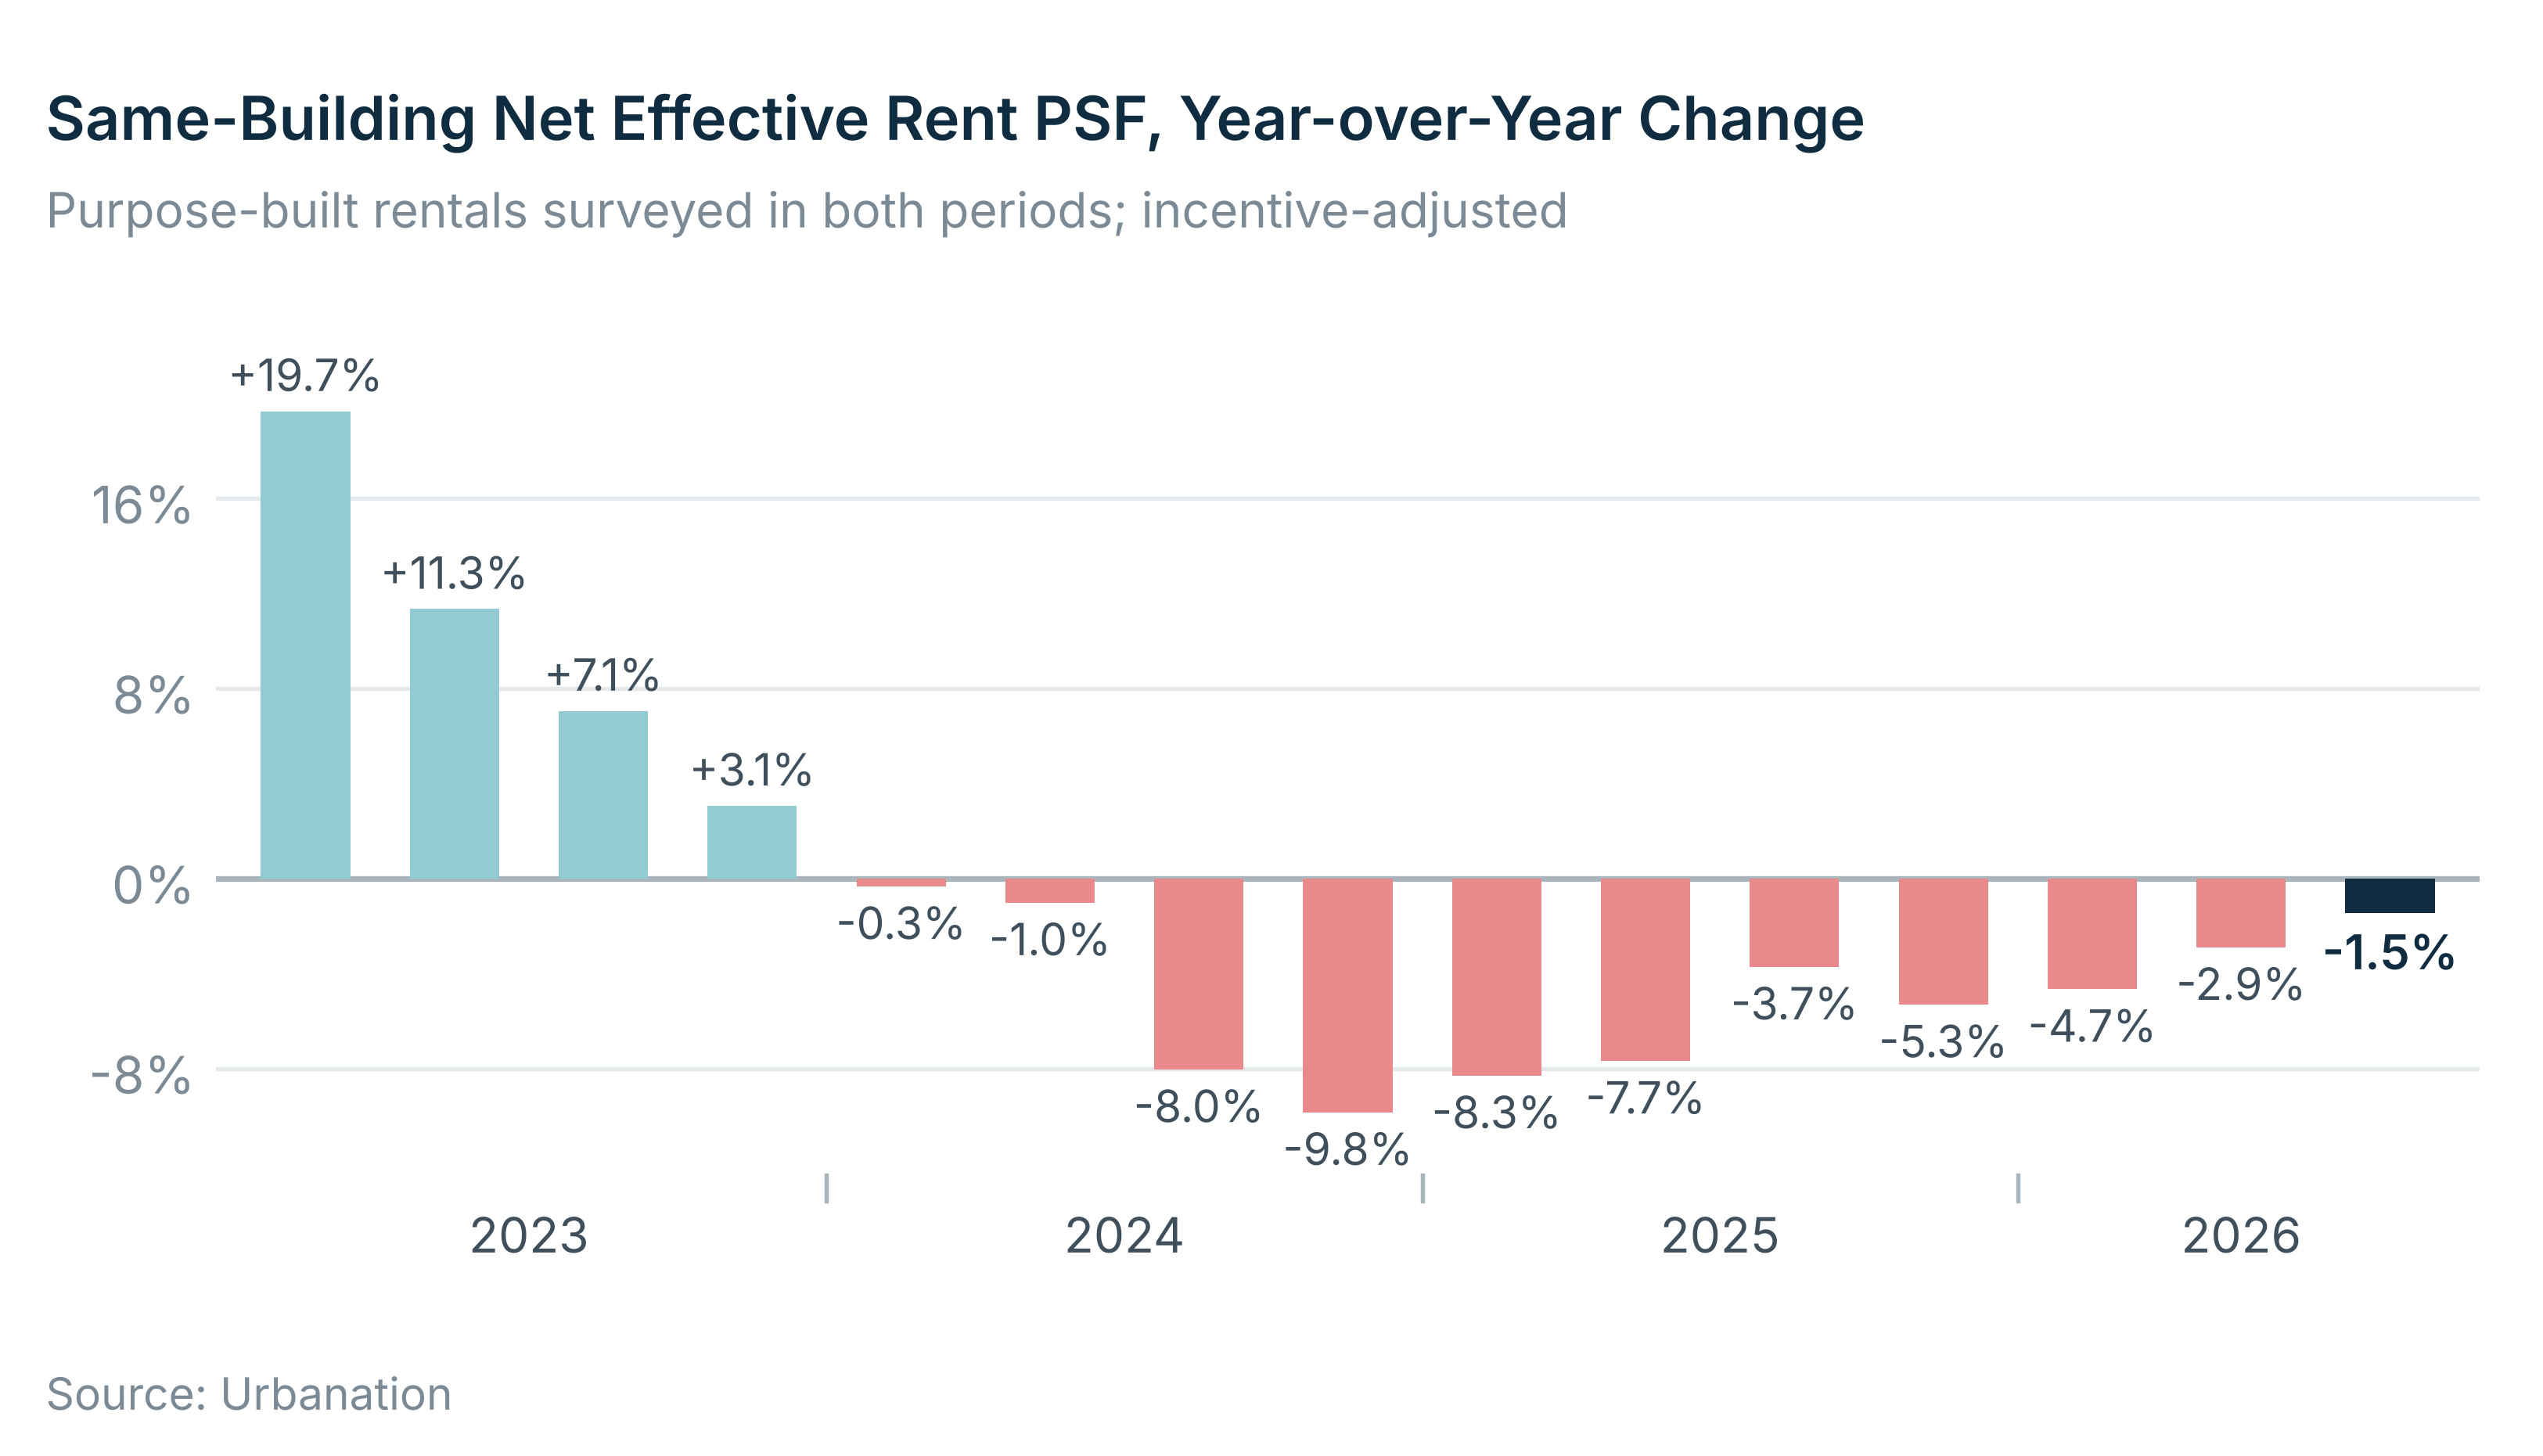
Rents turning higher. Average condo rents rose 2.4% from Q2 to $3.83 psf, the strongest third-quarter gain since 2023, and same-building purpose-built rents net of incentives rose 0.9%, the largest quarterly gain since Q3-2023. Annual declines narrowed to 0.6% for condos and 1.5% for purpose-built rentals, while condo rents in the Former City of Toronto rose 0.7%, the first annual increase in the core since early 2024.
“The Q3 data provides enough evidence to confirm that the GTHA rental market has entered a recovery phase. Rentals are leasing up at a record pace, vacancy is falling and landlords are pulling back on incentives, while available condo inventory is down more than 40% from its peak. The recovery in rents will gain momentum as overall rental supply declines, since the increase in purpose-built construction will only replace part of the drop in condo completions.”
Shaun Hildebrand, President of Urbanation
PURPOSE-BUILT RENTALS
Net absorption in purpose-built rentals completed since 2000 totalled 1,911 units in Q3, bringing the year-to-date total to a record 5,092 units, 22% above 2025 and 72% above the 10-year average. Absorption kept pace with a record 2,704 units completed in Q3. Vacancy in stabilized buildings (those that have reached 95% occupancy) declined for a third straight quarter to 3.0%, down from 3.5% a year ago, while vacancy in buildings at least one year old (which includes some buildings still in lease-up) fell to 5.8% from 6.8% in Q2 and 6.1% a year ago. Including all buildings in lease-up, total vacancy rose to 13.3% from 12.1% a year earlier due to the record volume of new units.
Landlords began pulling back on incentives. The share of projects offering incentives fell to 60% in Q3 from 67% in Q2, the largest quarterly decline since Q2-2022, and one month of free rent replaced two months as the most common offer. In buildings surveyed in both periods, rents net of incentives rose 0.9% from Q2, the largest quarterly gain since Q3-2023, and were down just 1.5% from a year ago, the smallest annual decline since Q2-2024. Average face rents were $4.11 psf ($2,921 for 710 sf).
CONDO RENTALS
Condo rental supply tightened sharply. Active listings fell 25% from a year ago to 3,705 units at the end of Q3, the largest annual decline since Q2-2022, and months of supply dropped to 0.7, below the long-term average of 1.0. Leases equalled 81% of listings, a level that has been followed by rising rents over the next year more than 80% of the time. Condo leasing reached a record 54,324 units over the first nine months, up 6% from 2025, while Q3 lease transactions of 20,175 were the second highest for a third quarter on record, with the 1% decline from last year’s peak entirely the result of fewer new completions.
Average condo rents rose 2.4% from Q2 to $3.83 psf ($2,604 for 681 sf), the strongest third-quarter gain since 2023, and were down just 0.6% from a year ago, the smallest decline since the downturn began in mid-2024. Downtown is leading the recovery. Condo rents in the Former City of Toronto rose 0.7% from a year ago, the first annual increase in the core since early 2024.
SUPPLY PIPELINE
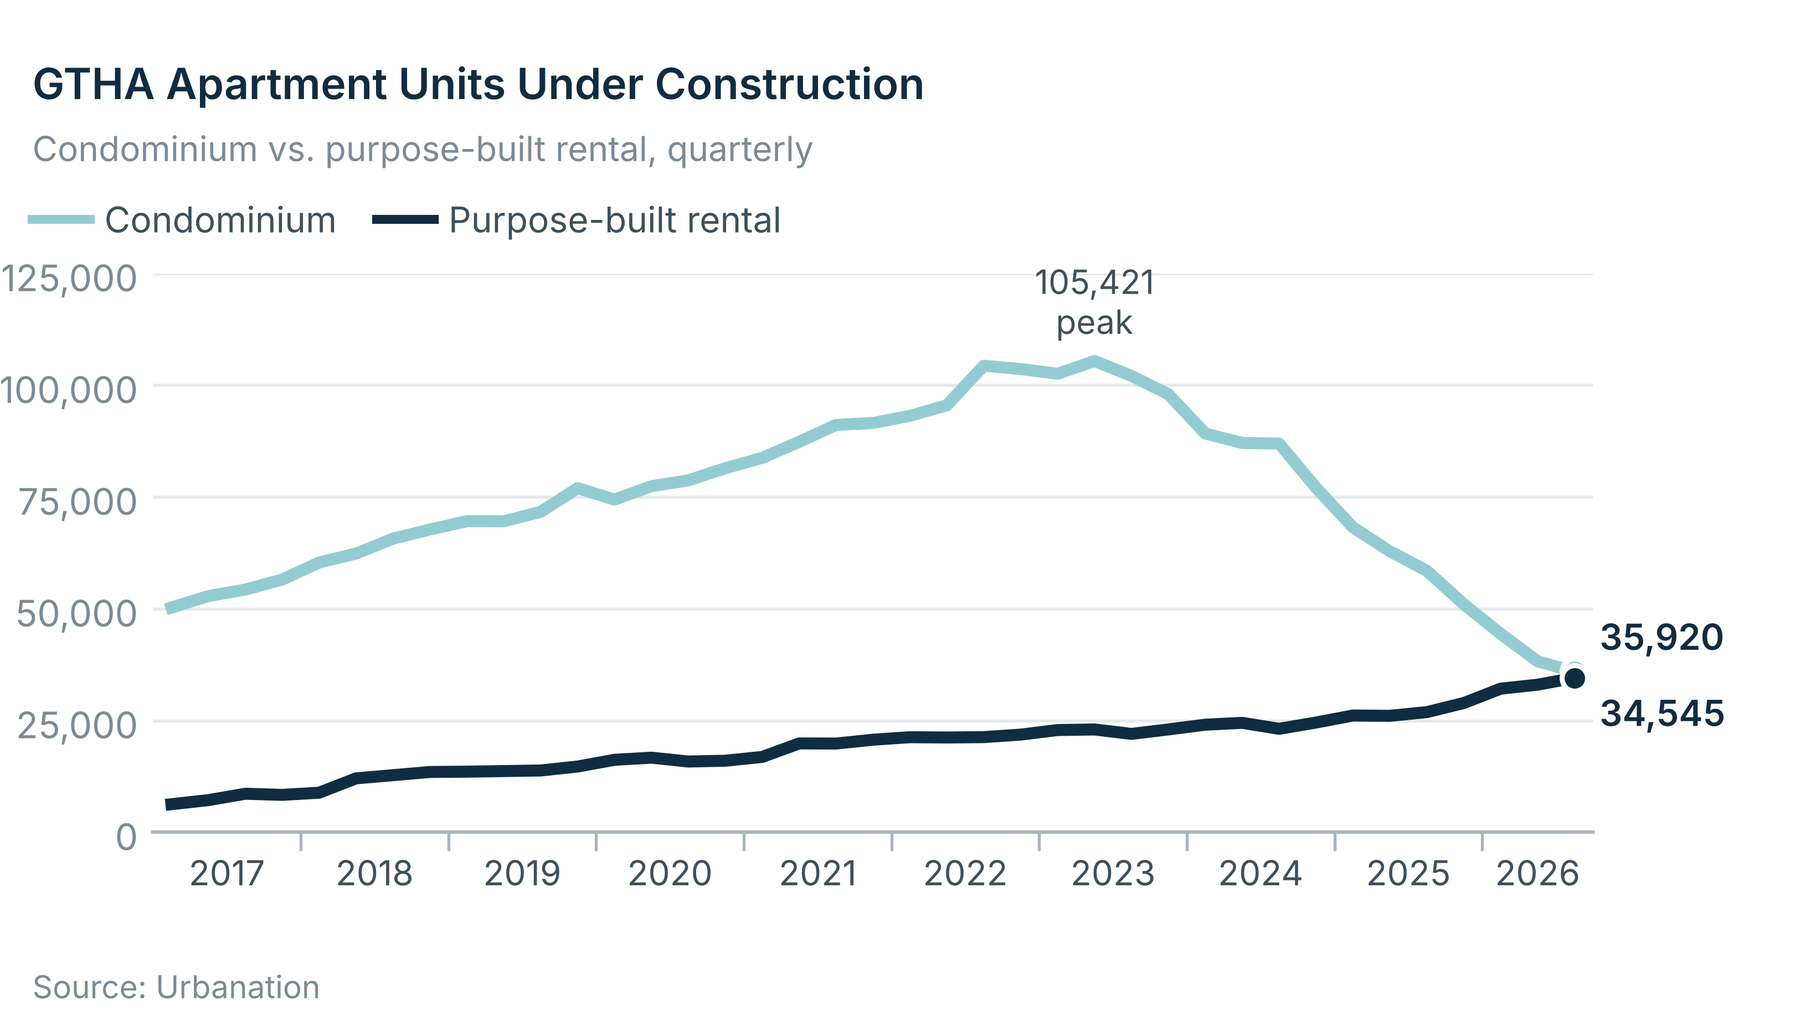
A multi-decade high of 5,067 purpose-built rental units started construction in Q3, up 172% from a year earlier. Starts over the first nine months totalled 12,106 units, up 82% from the same period of 2025 and already above the total for all of last year. Purpose-built units under construction reached 34,545, while condo units under construction fell 38% from a year ago to 35,920, the lowest level since early 2012. Purpose-built rentals now account for nearly half of all apartment units under construction in the GTHA.
Latest Research
October 27, 2026
Rental Recovery Begins in the GTHA as Vacancy and Incentives fallOctober 19, 2026
GTHA New Condo Sales Double from a Year Ago in Q3August 25, 2026
ONTARIO STILL FACING 121,000-UNIT RENTAL SHORTAGE DESPITE RECORD CONSTRUCTIONJuly 27, 2026
GTHA RENTAL MARKET SHOWS IMPROVEMENT IN Q2July 20, 2026
GTHA NEW CONDO SALES INCREASE OVER 50% IN Q2June 23, 2026
Ontario Student Housing Deliveries Set to Reach Record in 2026
In The News
October 20, 2026
Investors buying unsold Toronto condos at 40% discount to original selling price, report findsOctober 20, 2026
Almost half of Toronto area new condo sales are now bulk sales at a huge discountSeptember 24, 2026
High Art Capital pays $22.3 million to bulk buy 43 unsold condos along Eglinton LRT routeSeptember 23, 2026
Rents in tariff-exposed cities fall faster than those least affected by trade warAugust 25, 2026
Report finds Ontario’s rental housing gap persistsJuly 28, 2026
GTHA rental market shows improvement in Q2